
I talk up the merits of the New Economic School at a recruiting event here.
A Quick Theory of the Industrial Revolution (or, at least, an answer to 'Why Europe?')
Following a Twitter debate involving myself, Gabe Mathy, Pseudoerasmus, and Anton Howes on the theory that high wages in England induced labor-saving technologies and led to the Industrial Revolution, I thought I should lay out my own quick theory on why the Industrial Revolution happened in Britain, or at least, why in NW Europe. In short, this theory is too speculative to write an academic paper about (plus, this theory is not popular with Economic Historians, so it wouldn't publish), and I don't have enough time to write a book. Twitter doesn't provide enough space, so a blog post it will be.
 As far as we know, the high-wage economy that persisted in Europe after the Black Death was somewhat of an anomaly for the pre-Industrial world. Wages don't seem to have been as high in East Asia or India, while we actually don't know what wages were like in Africa. On the other hand, wages were even higher in many parts of the New World which had been recently depopulated, and where labor-land ratios were high. In any case, one can see the case for why economic agents would certainly try to cut back on high labor costs through new technologies. This theory has some sense, but I also see a few weaknesses. One is that "a wave of gadgets" swept over England at this time, with inventions including things like the flush toilet, which was not actually labor saving, and also the invention of calculus and of Malthusian economics. Also, many of the big technologies invented were actually quite simple, and so effective they would have been cost-effective to develop and implement at a wide range of relative prices/wages. A recent example of labor-saving technologies being worth it even for low labor costs is robots in low-wage China delivering mail.
Instead, I would focus on the other implication of high wages in a Malthusian world: fewer nutritional deficiencies, and higher human capital. This would include having consumers who can do more than simply buy necessities. High wages aren't enough, but rather I would think it's the size of human-capital adjusted population with which one is in contact with which will matter for technology growth. Thus, the Industrial Revolution could not have happened on a remote island with high wages, and would have been much less-likely in continents with North-South axis a la Jared Diamond. It also means that the rise of inter-continental trade would make overall technological growth faster, as technologies could be shared. This latter part of the story is probably crucial, as the rise of cheap American cotton was sure to be combined with the idea of mechanized textile factory production, especially since the latter had already been invented. (Indeed, one can't even produce cotton in England!)
The above logic could also answer why the IR didn't happen immediately after the Black Death. All I would argue is that if human capital is important for growth, then what we should expect to have seen after the BD in Europe is a relative "Golden Age" with a lot of progress and advance. In fact, the Black Death was the beginning of the end of the Dark Ages in Europe, as the Renaissance, the Age of Exploration, the Protestant Reformation, the Scientific Revolution, the Enlightenment, and the US Declaration of Independence all happened in the centuries thereafter. The printing press was invented in the 1450s in high-wage Germany. Modern banking was invented in Italy in the high-wage 1500s. Henry the Navigator had his formative years in the post-BD period of affluence in the 1410s. Brunelleschi discovered perspective in art in 1504. Newton invented the Calculus in the 1650s. The locus of technological change dramatically shifted to Europe -- before it had been a backwater. Europe then began colonizing the rest of the world. And, as it did, stagnant Eurasian agriculture imported a wealth of new agricultural technologies from the New World. However, I think it's better to view the Industrial Revolution not by itself as a special event, but as one of a long-line of major breakthroughs and accomplishments in the centuries after the Black Death, in which one sphere after another of European society was being transformed. Productivity soared in book-making after the introduction of the printing press, only there was much less elastic demand for books than there was for clothes and fashion, and so an Industrial Revolution could not depend on it. But the initial idea for mechanizing cotton textiles was probably not much larger or that much more difficult of a technological or intellectual breakthrough than these other revolutions, only it happened to be much more consequential in economic terms due to the nature of the industry.
The key difference between Europe and the rest of the world was that European cities and people were filthy, thus had high death rates which kept living standards high. This theory can also explain why "Not Southern Europe", as, for malthusian reasons, the post-Black Death high wages began to decline after around 1650 in the south. Note that this theory is also perfectly consistent with a cultural explanation for Britain's "wave of gadgets". A society in which half of the people suffer from protein deficiency is probably not going to be very vibrant culturally. Such a society may also develop institutions (the Inquisition) which place other barriers on development. Conversely, a society benefiting from high wages for Malthusian reasons might also be more likely to develop a culture and institutions conducive to economic growth.
In any case, this theory isn't completely new -- I've heard others, such as Brad DeLong, mention this as a possibility, but I haven't seen it explored in any detail. However, it won't be as popular with economists as the idea that growth is all about genetics. This idea was actually the first really big "Aha" moment I had after starting my Ph.D., as it popped right out of Greg Clark's excellent course on the Industrial Revolution, from where many of these ideas come. I eventually decided it was too speculative to write my dissertation on, so then switched to hysteresis in trade, and then to the collapse in US manufacturing employment. Maybe one day, post-tenure I'll return to growth...
Update: Pseudoerasmus points me to a very nice-looking paper by Kelly, Mokyr, and O' Grada, with a very similar theory to what I've written. They focus on England vs. France, and on the IR rather than everything which happened after the Black Death, and they don't appear to include Crosby-Diamond type effects, but I still approve.

Instead, I would focus on the other implication of high wages in a Malthusian world: fewer nutritional deficiencies, and higher human capital. This would include having consumers who can do more than simply buy necessities. High wages aren't enough, but rather I would think it's the size of human-capital adjusted population with which one is in contact with which will matter for technology growth. Thus, the Industrial Revolution could not have happened on a remote island with high wages, and would have been much less-likely in continents with North-South axis a la Jared Diamond. It also means that the rise of inter-continental trade would make overall technological growth faster, as technologies could be shared. This latter part of the story is probably crucial, as the rise of cheap American cotton was sure to be combined with the idea of mechanized textile factory production, especially since the latter had already been invented. (Indeed, one can't even produce cotton in England!)
The above logic could also answer why the IR didn't happen immediately after the Black Death. All I would argue is that if human capital is important for growth, then what we should expect to have seen after the BD in Europe is a relative "Golden Age" with a lot of progress and advance. In fact, the Black Death was the beginning of the end of the Dark Ages in Europe, as the Renaissance, the Age of Exploration, the Protestant Reformation, the Scientific Revolution, the Enlightenment, and the US Declaration of Independence all happened in the centuries thereafter. The printing press was invented in the 1450s in high-wage Germany. Modern banking was invented in Italy in the high-wage 1500s. Henry the Navigator had his formative years in the post-BD period of affluence in the 1410s. Brunelleschi discovered perspective in art in 1504. Newton invented the Calculus in the 1650s. The locus of technological change dramatically shifted to Europe -- before it had been a backwater. Europe then began colonizing the rest of the world. And, as it did, stagnant Eurasian agriculture imported a wealth of new agricultural technologies from the New World. However, I think it's better to view the Industrial Revolution not by itself as a special event, but as one of a long-line of major breakthroughs and accomplishments in the centuries after the Black Death, in which one sphere after another of European society was being transformed. Productivity soared in book-making after the introduction of the printing press, only there was much less elastic demand for books than there was for clothes and fashion, and so an Industrial Revolution could not depend on it. But the initial idea for mechanizing cotton textiles was probably not much larger or that much more difficult of a technological or intellectual breakthrough than these other revolutions, only it happened to be much more consequential in economic terms due to the nature of the industry.
The key difference between Europe and the rest of the world was that European cities and people were filthy, thus had high death rates which kept living standards high. This theory can also explain why "Not Southern Europe", as, for malthusian reasons, the post-Black Death high wages began to decline after around 1650 in the south. Note that this theory is also perfectly consistent with a cultural explanation for Britain's "wave of gadgets". A society in which half of the people suffer from protein deficiency is probably not going to be very vibrant culturally. Such a society may also develop institutions (the Inquisition) which place other barriers on development. Conversely, a society benefiting from high wages for Malthusian reasons might also be more likely to develop a culture and institutions conducive to economic growth.
In any case, this theory isn't completely new -- I've heard others, such as Brad DeLong, mention this as a possibility, but I haven't seen it explored in any detail. However, it won't be as popular with economists as the idea that growth is all about genetics. This idea was actually the first really big "Aha" moment I had after starting my Ph.D., as it popped right out of Greg Clark's excellent course on the Industrial Revolution, from where many of these ideas come. I eventually decided it was too speculative to write my dissertation on, so then switched to hysteresis in trade, and then to the collapse in US manufacturing employment. Maybe one day, post-tenure I'll return to growth...
Update: Pseudoerasmus points me to a very nice-looking paper by Kelly, Mokyr, and O' Grada, with a very similar theory to what I've written. They focus on England vs. France, and on the IR rather than everything which happened after the Black Death, and they don't appear to include Crosby-Diamond type effects, but I still approve.
How to signin to keycloak using google
There are 3 set of steps that we must follow in order to come up with a web project that will allow us to login using google's identity provider.
Set 1 - Create a google application
- Create a google application at https://console.developers.google.com

- Set OAuth consent screen

- Fill up the requirement to create a client id

- Save the client id and secret, we will use it later when creating a client in keycloak


Set 2 - Setup Keycloak
- Create realm social-oauth
- Create Identity Provider
- Identity Provider
- Add provider
- Copy the client id and secret that we save earlier in their respective fields
- Create a new keycloak application client
- While in the client, click the Installation tab
- Under format option select "Keycloak OIDC JSON"
- Copy and paste this value in a file named keycloak.json inside your javaee7 web project's web-inf directory.


Set 3 - Create our web project
- Create a new maven project using javaee7 blank archetype, name it social-oauth-demo.
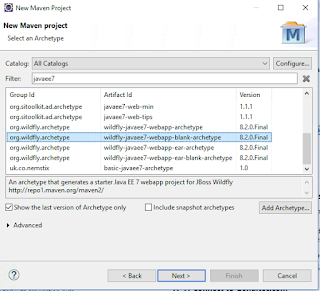
- Create a file name keycloak.json, content will be coming from the keycloak client that we just created.
It should look like this:{
"realm": "social-auth",
"auth-server-url": "http://localhost:8180/auth",
"ssl-required": "external",
"resource": "social-auth-client",
"public-client": true
} - Create web.xml file, where we will specify keycloak as the authentication method. Also secure a web resource.
<?xml version="1.0" encoding="UTF-8"?>
<web-app xmlns:xsi="http://www.w3.org/2001/XMLSchema-instance"
 xmlns="http://java.sun.com/xml/ns/javaee" xmlns:web="http://java.sun.com/xml/ns/javaee/web-app_3_0.xsd"
 xsi:schemaLocation="http://java.sun.com/xml/ns/javaee http://java.sun.com/xml/ns/javaee/web-app_3_0.xsd"
 version="3.0">

 <module-name>social-auth-demo</module-name>

 <security-constraint>
  <web-resource-collection>
   <web-resource-name>All Pages</web-resource-name>
   <url-pattern>/social/*</url-pattern>
  </web-resource-collection>
  <auth-constraint>
   <role-name>social-access</role-name>
  </auth-constraint>
 </security-constraint>

 <login-config>
  <auth-method>KEYCLOAK</auth-method>
  <realm-name>social-auth</realm-name>
 </login-config>
 <security-role>
  <role-name>social-access</role-name>
 </security-role>

</web-app> - Build and deploy the war in wildfly. Make sure that wildfly has keycloak client installed.
- Open a browser and enter http://localhost:8080/social-auth-demo/social/index.html, this should redirect to keycloak's login page. You should see a google icon to login.


The same logic applies to facebook.
Fiscal over monetary policy?
The Economy May Be Stuck in a Near-Zero World (Justin Wolfers).
Justin does a good job describing how many economists view the role of monetary and fiscal policy in the post Great Recession world of low interest rates and low inflation. I am curious to know where I agree and disagree with what he says. So, here goes.
[T]he real (inflation-adjusted) interest rate consistent with the economy operating at its full potential has fallen...from around 2.5 percent to 1 percent, or lower.
I think this is true. I also do not think it's surprising that the "natural rate of interest" (r*) fluctuates and that its trend path may shift over time. Indeed, I'd be surprised to learn this was not the case. According to standard macroeconomic theory, r* should follow the trend in consumption growth. The basic idea is simple. If the economy is expected to grow rapidly, people will want to save less (or borrow against their higher future income) in order to smooth their consumption. Collectively, their efforts to consume more and save less puts upward pressure on the real interest rate. The converse holds true if pessimism reigns: people will want to save more, to make provisions against a bleak future. Collectively, the effect is to depress the real interest rate.
Of course, we cannot observe r*. But theory suggests it should be roughly proportional to consumption growth. We can observe consumption growth. Here is what the growth rate of real (inflation-adjusted) consumption of nondurables and services in the postwar U.S. looks like (series is smoothed):

If you're trained in the art of haruspicy, as most of us appear to be, then you'll divine all sorts of patterns from the picture above. You might see a 2 percent trend growth rate with a break down to 1 percent (or lower) in either 2000 or 2007. You might even detect a decade-long era of low growth in the 1970s.
Combined with the Fed's 2 percent inflation target, this implies...
In "normal times," the nominal interest rate -- the neutral interest rate plus inflation -- has fallen from around 6 percent to 3 percent. That creates a serious problem for the Fed. Here's why: Most recessions can be cured by lowering rates by several percentage points. When interest rates were closer to 6 percent, the Fed could lift the economy with plenty of leeway.
This is textbook stuff, which is not the same thing as saying it's correct. My own view on the matter (which is not necessarily correct either) is that the Fed is largely constrained to follow what the market "wants" in the way of real interest rates. It's not that the Fed "cures" a recession by lowering its policy rate -- the Fed is accommodating market forces that would have driven the real interest rate lower even in the absence of a central bank. Rightly or wrongly, the Fed acts to "smooth" these interest rate adjustments in the short-run. But at the end of the day, the trend path of r* is beyond the control of the Fed.
Yes, but what if r* is so low that the effective zero lower bound (ZLB) on the short-term nominal interest rate (the Fed's policy rate) prevents the Fed from accommodating what the market wants? With 2 percent inflation, the real interest rate can only decline to -2%. What if that's not low enough? Then something else has to give--for example, the unemployment rate will rise and remain elevated for as long as this unfortunate situation persists--a secular stagnation.
Perhaps the answer lies outside the Fed. It may be time to revive a more active role for fiscal policy--government spending and taxation--so that the government fills in for the missing stimulus when the Fed can't cut rates any further. Given political realities, this may be best achieved by building in stronger automatic stabilizers, mechanisms to increase spending in bad times, without requiring Congressional action.
In this spirit, Justin recommends a mechanism that automatically increases funding for infrastructure programs when economic growth slows. I personally don't think this is a terrible idea. (Though, I'd rather that infrastructure be geared more to long-term needs.) But no doubt it's probably easier said than done.
Sometimes though, when I sit back and reflect on this line of thinking, it strikes me as rather odd in a couple of respects.
First, is the ZLB really a significant economic problem? If it is, then why not abolish it as recommended by Miles Kimball? Would permitting significantly negative real rates of interest solve our problems? I don't think so. I'm inclined to think of a low r* as symptomatic of more fundamental economic forces. And eliminating any (real or perceived) gap between the market interest rate and r* is probably small potatoes (see here).
If r* is low, then we need to ask why it is low. There's no shortage of possible explanations out there (low productivity growth, demographics, etc.). If we somehow decide we'd like to see it higher, the solution is likely to be found in growth-promoting policies. (Whether we want growth-promoting policies is a completely separate matter, by the way. Personally, I think more attention should be paid to policies that encourage social cohesion, which may or may not be consistent with higher growth. But this is a column for another day.)
Second, I think the world has indeed changed for discretionary monetary and fiscal policy, but in a way that almost no one talks about. Quite apart from any possible changes in r* (which we cannot measure), the real rate of return on U.S. Treasury (UST) debt--what my boss James Bullard calls "r-dagger"--has been declining for over 30 years (diagram taken from here).

One interpretation of this pattern is that USTs were initially a flight-to-safety vehicle with the disruptions that occurred in the early 1970s (so real yields declined). With the breakdown of Bretton Woods and fiscal pressures (Vietnam war, War on Poverty, etc.), however, inflation became un-anchored. The high real yield on nominal UST debt reflected a growing inflation-risk premium in the early 1980s (when inflation was high and volatile). Subsequently, as inflation declined and inflation expectations became anchored (thanks to Volcker and a terrible recession) the inflation risk premium declined over time. Since about 2000, a China trade shock and other factors led to a growing world demand for USDs and USTs. R-dagger (r+) remains extremely low even today--reflecting the "liquidity premium" that the market now attaches to UST debt.
Moreover, the distinction between USDs and USTs is much diminished in financial markets. In the old days, when the Fed wanted to move interest rates through an open-market swap of USD for UST, it meant something. But today, it means almost nothing, since interest-bearing reserves are a very close substitute for interest-bearing treasuries. In short, U.S. treasury debt is essentially "money" as far as financial markets are concerned (USTs circulate as such in repo markets, for example).
The implication of all this for monetary and fiscal policy is quite interesting. The fact that the yield on USTs is less than (our estimate of) the natural rate of interest suggests that the policy rate is presently too low -- not too high (as is suggested by standard ZLB concerns). The most direct way to raise interest rates (i.e., eliminate the liquidity premium on USTs) is for the U.S. treasury to issue debt at a faster pace. One way to do this is through Justin's automatic infrastructure funding plan that kicks in when liquidity premia on USTs are elevated (bond yields are low). Another way is to have automatic (temporary) tax cuts kick in. Yet another way (though far less desirable) is to have the Fed increase the interest in pays on reserves. Politically this is dynamite, but from an economic perspective, it forces (ceteris paribus) the treasury to issue debt at a faster pace (because it lowers Fed remittances to the treasury). Yet another way is to have the Fed sell some of its treasury holdings (since treasuries are sometimes more liquid than reserves in financial markets--i.e., only depository institutions have direct access to reserves).
Depending on which view one adopts, the recommended Fed policy action matters a great deal (at least, in principle, if not quantitatively). If the interest rate is too high (ZLB view), then it should be lowered, or the inflation target raised. If the interest rate is too low (liquidity premium view), then it should be raised, through asset sales or some other mechanism.
On the other hand, the recommended Treasury policy action seems robust across the two views: the treasury should expand its debt at a faster pace (via tax cuts or increased spending, or some combination). This seems like a promising development from the perspective of competing theories. If a policy recommendation follows from many different perspectives, we become more comfortable with the idea of actually implement them. Of course, there are some caveats to consider, which I discuss here. But enough for today.
Justin does a good job describing how many economists view the role of monetary and fiscal policy in the post Great Recession world of low interest rates and low inflation. I am curious to know where I agree and disagree with what he says. So, here goes.
[T]he real (inflation-adjusted) interest rate consistent with the economy operating at its full potential has fallen...from around 2.5 percent to 1 percent, or lower.
I think this is true. I also do not think it's surprising that the "natural rate of interest" (r*) fluctuates and that its trend path may shift over time. Indeed, I'd be surprised to learn this was not the case. According to standard macroeconomic theory, r* should follow the trend in consumption growth. The basic idea is simple. If the economy is expected to grow rapidly, people will want to save less (or borrow against their higher future income) in order to smooth their consumption. Collectively, their efforts to consume more and save less puts upward pressure on the real interest rate. The converse holds true if pessimism reigns: people will want to save more, to make provisions against a bleak future. Collectively, the effect is to depress the real interest rate.
Of course, we cannot observe r*. But theory suggests it should be roughly proportional to consumption growth. We can observe consumption growth. Here is what the growth rate of real (inflation-adjusted) consumption of nondurables and services in the postwar U.S. looks like (series is smoothed):

If you're trained in the art of haruspicy, as most of us appear to be, then you'll divine all sorts of patterns from the picture above. You might see a 2 percent trend growth rate with a break down to 1 percent (or lower) in either 2000 or 2007. You might even detect a decade-long era of low growth in the 1970s.
Combined with the Fed's 2 percent inflation target, this implies...
In "normal times," the nominal interest rate -- the neutral interest rate plus inflation -- has fallen from around 6 percent to 3 percent. That creates a serious problem for the Fed. Here's why: Most recessions can be cured by lowering rates by several percentage points. When interest rates were closer to 6 percent, the Fed could lift the economy with plenty of leeway.
This is textbook stuff, which is not the same thing as saying it's correct. My own view on the matter (which is not necessarily correct either) is that the Fed is largely constrained to follow what the market "wants" in the way of real interest rates. It's not that the Fed "cures" a recession by lowering its policy rate -- the Fed is accommodating market forces that would have driven the real interest rate lower even in the absence of a central bank. Rightly or wrongly, the Fed acts to "smooth" these interest rate adjustments in the short-run. But at the end of the day, the trend path of r* is beyond the control of the Fed.
Yes, but what if r* is so low that the effective zero lower bound (ZLB) on the short-term nominal interest rate (the Fed's policy rate) prevents the Fed from accommodating what the market wants? With 2 percent inflation, the real interest rate can only decline to -2%. What if that's not low enough? Then something else has to give--for example, the unemployment rate will rise and remain elevated for as long as this unfortunate situation persists--a secular stagnation.
Perhaps the answer lies outside the Fed. It may be time to revive a more active role for fiscal policy--government spending and taxation--so that the government fills in for the missing stimulus when the Fed can't cut rates any further. Given political realities, this may be best achieved by building in stronger automatic stabilizers, mechanisms to increase spending in bad times, without requiring Congressional action.
In this spirit, Justin recommends a mechanism that automatically increases funding for infrastructure programs when economic growth slows. I personally don't think this is a terrible idea. (Though, I'd rather that infrastructure be geared more to long-term needs.) But no doubt it's probably easier said than done.
Sometimes though, when I sit back and reflect on this line of thinking, it strikes me as rather odd in a couple of respects.
First, is the ZLB really a significant economic problem? If it is, then why not abolish it as recommended by Miles Kimball? Would permitting significantly negative real rates of interest solve our problems? I don't think so. I'm inclined to think of a low r* as symptomatic of more fundamental economic forces. And eliminating any (real or perceived) gap between the market interest rate and r* is probably small potatoes (see here).
If r* is low, then we need to ask why it is low. There's no shortage of possible explanations out there (low productivity growth, demographics, etc.). If we somehow decide we'd like to see it higher, the solution is likely to be found in growth-promoting policies. (Whether we want growth-promoting policies is a completely separate matter, by the way. Personally, I think more attention should be paid to policies that encourage social cohesion, which may or may not be consistent with higher growth. But this is a column for another day.)
Second, I think the world has indeed changed for discretionary monetary and fiscal policy, but in a way that almost no one talks about. Quite apart from any possible changes in r* (which we cannot measure), the real rate of return on U.S. Treasury (UST) debt--what my boss James Bullard calls "r-dagger"--has been declining for over 30 years (diagram taken from here).

One interpretation of this pattern is that USTs were initially a flight-to-safety vehicle with the disruptions that occurred in the early 1970s (so real yields declined). With the breakdown of Bretton Woods and fiscal pressures (Vietnam war, War on Poverty, etc.), however, inflation became un-anchored. The high real yield on nominal UST debt reflected a growing inflation-risk premium in the early 1980s (when inflation was high and volatile). Subsequently, as inflation declined and inflation expectations became anchored (thanks to Volcker and a terrible recession) the inflation risk premium declined over time. Since about 2000, a China trade shock and other factors led to a growing world demand for USDs and USTs. R-dagger (r+) remains extremely low even today--reflecting the "liquidity premium" that the market now attaches to UST debt.
Moreover, the distinction between USDs and USTs is much diminished in financial markets. In the old days, when the Fed wanted to move interest rates through an open-market swap of USD for UST, it meant something. But today, it means almost nothing, since interest-bearing reserves are a very close substitute for interest-bearing treasuries. In short, U.S. treasury debt is essentially "money" as far as financial markets are concerned (USTs circulate as such in repo markets, for example).
The implication of all this for monetary and fiscal policy is quite interesting. The fact that the yield on USTs is less than (our estimate of) the natural rate of interest suggests that the policy rate is presently too low -- not too high (as is suggested by standard ZLB concerns). The most direct way to raise interest rates (i.e., eliminate the liquidity premium on USTs) is for the U.S. treasury to issue debt at a faster pace. One way to do this is through Justin's automatic infrastructure funding plan that kicks in when liquidity premia on USTs are elevated (bond yields are low). Another way is to have automatic (temporary) tax cuts kick in. Yet another way (though far less desirable) is to have the Fed increase the interest in pays on reserves. Politically this is dynamite, but from an economic perspective, it forces (ceteris paribus) the treasury to issue debt at a faster pace (because it lowers Fed remittances to the treasury). Yet another way is to have the Fed sell some of its treasury holdings (since treasuries are sometimes more liquid than reserves in financial markets--i.e., only depository institutions have direct access to reserves).
Depending on which view one adopts, the recommended Fed policy action matters a great deal (at least, in principle, if not quantitatively). If the interest rate is too high (ZLB view), then it should be lowered, or the inflation target raised. If the interest rate is too low (liquidity premium view), then it should be raised, through asset sales or some other mechanism.
On the other hand, the recommended Treasury policy action seems robust across the two views: the treasury should expand its debt at a faster pace (via tax cuts or increased spending, or some combination). This seems like a promising development from the perspective of competing theories. If a policy recommendation follows from many different perspectives, we become more comfortable with the idea of actually implement them. Of course, there are some caveats to consider, which I discuss here. But enough for today.
The Real Exchange Rates and Trade Literature
Noah Smith asks about the literature on the real exchange rate (RER) and trade.
My own main line of research is about RERs and manufacturing (also here on workers), RER measurement, and I've also done work on the impact of currency unions on trade, or lack thereof.
The first and third of these papers does include a bit on trade, although in neither case is it the focus. The third paper shows that the class of Weighted-Average Relative (WAR) exchange rates does a better job predicting US trade balances than do traditional indices. The difference is largely that the WAR indices reflect the impact of increased trade with the People's Republic of China. (In truth, the WARP index was first discovered by Thomas, Fahle, and Marquez in a very under-rated paper...)

I've also looked recently while prepping for class on a good paper on RERs and trade. In truth, the answer is that I also couldn't really find good, modern work that takes identification seriously (if you know of some, please add in the comments. Actually, when I began working on RERs and manufacturing employment, I could see that this literature had already become quite dated. Results were mixed, the best paper was still before the era in which standard errors were clustered in one direction much less two, each paper implied something different (of the four most recent using US data, one said RERs had only a small impact, a second said the impact depended on the specification, and a third said it had none, and a fourth said it was large), and the literature seemed to me in need of a modern treatment. However, I got a lot of pushback from the first time I presented this paper that the topic had "already been done". I think part of this stems from a certain gullability, and over-confidence among certain economists in their profession. If a paper is published in a good journal, then that's the end of the story. It must be true. Even if the paper was from 1991, and the results came from 600 data points and included few controls, and barely any robustness. In truth, I suspect that probably more than half of published research is straight wrong. In addition, much of what is "right" might offer incomplete evidence, or still has plenty of room for improvement. A perfect paper probably does not exist, and so I see papers that subject already published research results to new tests as being helpful, and quite worthy of publication in top field journals. (This is almost certainly a minority opinion...)
One thing I probably overlooked is simply that the literature on RERs and trade isn't that great. I'm still contemplating doing a paper on this, although I'm sure I'd have a lot of similar pushback. ("This result is not new.") The big issue in this literature is identification. In theory, the correlation between the RER and trade could go in either direction. That's because something like the Asian Financial Crisis could cripple the industrial (tradable) sector and also lead to a severe currency depreciation. Thus, the raw correlation between trade and the RER could be negative, positive, or zero in the aggregate. I haven't seen anyone really try to solve the identification problem here. (Well, OK, there was an economic history paper that looked at countries which pegged to gold vs. silver, and then what happened when the price of gold to silver changes, but what it seemed to me to miss was that this also had implications for monetary policy, and so wasn't quite exogenous.)
In any case, the end conclusion is that this is very much a literature in need of improvement.
My own main line of research is about RERs and manufacturing (also here on workers), RER measurement, and I've also done work on the impact of currency unions on trade, or lack thereof.
The first and third of these papers does include a bit on trade, although in neither case is it the focus. The third paper shows that the class of Weighted-Average Relative (WAR) exchange rates does a better job predicting US trade balances than do traditional indices. The difference is largely that the WAR indices reflect the impact of increased trade with the People's Republic of China. (In truth, the WARP index was first discovered by Thomas, Fahle, and Marquez in a very under-rated paper...)

I've also looked recently while prepping for class on a good paper on RERs and trade. In truth, the answer is that I also couldn't really find good, modern work that takes identification seriously (if you know of some, please add in the comments. Actually, when I began working on RERs and manufacturing employment, I could see that this literature had already become quite dated. Results were mixed, the best paper was still before the era in which standard errors were clustered in one direction much less two, each paper implied something different (of the four most recent using US data, one said RERs had only a small impact, a second said the impact depended on the specification, and a third said it had none, and a fourth said it was large), and the literature seemed to me in need of a modern treatment. However, I got a lot of pushback from the first time I presented this paper that the topic had "already been done". I think part of this stems from a certain gullability, and over-confidence among certain economists in their profession. If a paper is published in a good journal, then that's the end of the story. It must be true. Even if the paper was from 1991, and the results came from 600 data points and included few controls, and barely any robustness. In truth, I suspect that probably more than half of published research is straight wrong. In addition, much of what is "right" might offer incomplete evidence, or still has plenty of room for improvement. A perfect paper probably does not exist, and so I see papers that subject already published research results to new tests as being helpful, and quite worthy of publication in top field journals. (This is almost certainly a minority opinion...)
One thing I probably overlooked is simply that the literature on RERs and trade isn't that great. I'm still contemplating doing a paper on this, although I'm sure I'd have a lot of similar pushback. ("This result is not new.") The big issue in this literature is identification. In theory, the correlation between the RER and trade could go in either direction. That's because something like the Asian Financial Crisis could cripple the industrial (tradable) sector and also lead to a severe currency depreciation. Thus, the raw correlation between trade and the RER could be negative, positive, or zero in the aggregate. I haven't seen anyone really try to solve the identification problem here. (Well, OK, there was an economic history paper that looked at countries which pegged to gold vs. silver, and then what happened when the price of gold to silver changes, but what it seemed to me to miss was that this also had implications for monetary policy, and so wasn't quite exogenous.)
In any case, the end conclusion is that this is very much a literature in need of improvement.
Some International Data on Industrial Robots
Via Adam Tooze on Twitter. The picture quality is poor, but here it is below. The US in fact has fewer robots than Germany and Japan, and yet manufacturing employment has fallen by more.


The Gold Standard, the Great Depression, and the Brilliance of NES Students...
Tomorrow's lecture is, in part, covering a homework on the Great Depression in which the students were asked to redo some of a classic Bernanke and James article on the Great Depression. It's a great article, although the empirics -- like all empirics from the early 1990s -- are quite dated. This actually makes it good to assign, in my view, as it makes it relatively easy for students to suggest improvements. The first time I assigned this, I had a student (A.A.) who wasn't quite happy with the limited information contained in a regression of Industrial Production on gold standard status. Thus, she created this. It makes it clear, aside from the wonders of conditional formatting. There are two things this makes obvious: (1) the later you abandon the gold standard, the worse you did. And, (2) at first, if anything, the gold dead-enders were doing slightly better (or as well), but the further they went the worse they did. It blew my mind. Absolutely brilliant table for an undergraduate to turn in for a two page essay. Go back and have a look at the Bernanke/James tables and compare. There's no comparison. I have a feeling she, and many others I've had the good fortune to teach, will go on to do great things).


